 Business Vehicles Commercial Insurance
Business Vehicles Insurance for Vans, Pickups, Box Trucks & Tractors in the USA
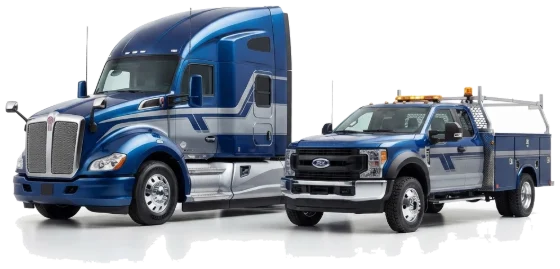
Add passenger vehicles, cargo vans, service pickups, box trucks, Class 8 tractors, car haulers, and specialized hauling trailers on one structured U.S. commercial auto request.
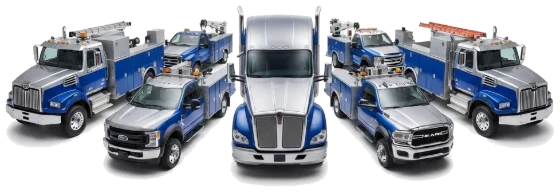
U.S. businesses rely on a wide mix of commercial vehicles — from sales sedans, service pickups, and Sprinter cargo vans to 26ft box trucks, car haulers, and Class 8 semi-tractors. InsurixPro is an independent insurance agency that structures commercial auto and trucking coverage around the exact vehicles and trailers your business operates.
- Licensed in: Georgia & authorized states (view matrix)
- Based in: Atlanta, GA, USA
- No obligation to request a quote
- No SSN or payment required in the initial step
Multi-Carrier Shop
Compare multiple US insurance carriers from one single online application.
Fast COI & Filings
Prompt certificates of insurance (COI), BMC-91 & SR-22 filing support.
New Authorities Welcome
Dedicated programs for new USDOT/MC numbers, box trucks & owner-operators.
Licensed Independent Advice
Transparent coverage comparisons with zero obligation to buy.
Intended Customer Profile
Who This Coverage Is For: Motor Carriers, Vehicles & Drivers
InsurixPro is an independent insurance agency structuring business vehicles commercial insurance programs for commercial trucking operators whose vehicles, drivers, contracts, or motor carrier authority require specialized protection:
- Contractors, HVAC, plumbing, electrical, and construction companies running pickups and utility vans
- Courier, parcel, appliance, and final-mile delivery businesses operating cargo vans and box trucks
- For-hire motor carriers and private fleets running semi-tractors, flatbeds, and car haulers
- Small businesses and corporations insuring company cars, SUVs, and multi-vehicle commercial schedules
Key Operational Risks Addressed
- • Claim denials on personal auto policies when a vehicle is used for commercial delivery, job-site travel, or hauling
- • Uninsured upfit losses when liftgates, custom boxes, or service bodies are omitted from stated value
- • Contractual COI rejections when vehicle liability limits fall below general contractor or shipper minimums
- • Registration or lender penalties when financed business vehicles lack commercial Loss Payee endorsements
Core Policy Lines & Endorsements
Commercial Trucking, Box Truck & Car Hauler Coverage Options
Coverage limits, deductibles, and endorsements are structured around your equipment, shipper contracts, and operating authority:
- Commercial Auto Liability ($300,000, $500,000, or $1,000,000+ Combined Single Limit for U.S. business vehicles)
- Vehicle Physical Damage (Comprehensive & Collision based on Stated Amount or Actual Cash Value)
- Scheduled Coverage for Permanently Attached Upfits, Liftgates, Service Bodies & Reefer Units
- Hired & Non-Owned Auto (HNOA) Liability for rented trucks and employee-owned vehicles used on business errands
Exclusions & Policy Terms to Verify
- • Portable tools, detached machinery, and cargo inside the vehicle are not covered by vehicle physical damage alone — they require Inland Marine (Tool Floater) or Motor Truck Cargo coverage
- • Unscheduled vehicles acquired mid-policy term must be reported within the policy acquisition window required by the carrier
FMCSA & Motor Carrier Filings Requirements
- GVWR-Based Underwriting & DOT Thresholds: Vehicles with a Gross Vehicle Weight Rating (GVWR) of 10,001+ lbs operating interstate in commerce are subject to FMCSA safety rules and 49 CFR Part 387 financial responsibility minimums
- Commercial Title vs. Personal Registration Alignment: Underwriters verify whether business vehicles are titled to an LLC/Corporation or an individual sole proprietor and issue corresponding Symbol 7 (Specifically Described Autos) or Symbol 1 policy schedules
- Permanently Attached Equipment & Upfits: Ladder racks, utility service bodies, hydraulic liftgates, refrigeration units, and toolboxes must be included in the vehicle stated value to avoid coinsurance or physical damage gaps
- Scheduled Trailers & Towed Equipment: Utility trailers, gooseneck flatbeds, enclosed cargo trailers, and multi-car auto transport trailers require separate VIN scheduling for liability and physical damage protection
What Affects Your Premium for Vehicles & Drivers
Premiums vary materially by state, authority age, driving history, equipment value, cargo, radius, limits and loss history:
- Vehicle weight class (Light Class 1–2, Medium Class 3–6 box trucks, Heavy Class 7–8 tractors) and body type
- Stated vehicle value, upfit equipment value, and chosen Comprehensive/Collision deductibles
- Garaging ZIP code, daily trips per day, and local vs. regional/interstate operating radius
- Assigned commercial drivers, MVR histories, and prior business auto insurance continuity
What You Need for a Quote
- 17-character VIN, year, make, model, and body type for every pickup, van, box truck, tractor, and trailer
- Verified GVWR and current market/stated value (including permanently attached equipment)
- Garaging address and finance/lease company contact details for each financed unit
- Roster of commercial drivers who operate the business vehicles
New Authority Considerations
- VIN-Level Accuracy: Every commercial vehicle, box truck, cargo van, or tractor must be submitted with its 17-character VIN, verified GVWR, and garaging ZIP code
- Mixed Fleet Support: InsurixPro allows U.S. businesses to combine light-duty company cars/pickups with medium-duty box trucks and heavy-duty tractors in one guided intake
- Lender & Lessor Proof: Loss Payee and Additional Insured Lessor endorsements are matched per vehicle VIN for financed or leased business equipment
- Valid 17-digit VIN, model year, make, body style, and verified GVWR for each business vehicle and trailer
Need help confirming your FMCSA filings, cargo sub-limits, or new authority documents?
Speak directly with a licensed producer or run our free interactive 2027 New Authority & FMCSA Filing Calculator.
Related Regulatory & Coverage Guides
Explore Related Commercial Trucking & Auto Programs
View Trucking & Transportation Pillar Hub →Helpful answers before you begin
Frequently Asked Questions
Can I insure pickups, cargo vans, and box trucks on the same commercial auto request?
Yes. Our commercial intake supports passenger vehicles, cargo/Sprinter vans, pickups, utility trucks, box trucks, semi-tractors, and trailers so your independent insurance agency team can match the right commercial auto or motor carrier market.
Does vehicle physical damage cover my liftgate or utility service body?
Permanently attached equipment such as a hydraulic liftgate, utility body, or refrigeration unit can be covered when properly declared and included in the vehicle stated amount on the commercial policy schedule.
What if my business vehicle is registered in my personal name?
Many sole proprietors and single-member LLC owners have vehicles titled in their personal name. Our application records whether registration is under your personal name or business name so underwriters can format the policy properly.
No-Obligation Multi-Carrier Review
Request a Quote With Our Independent Insurance Agency
Share your vehicles, drivers, operating radius, and USDOT filings details to compare business vehicles commercial insurance options with a licensed InsurixPro producer.
Ready to compare your commercial trucking or auto insurance options?
Start your online quote in under two minutes or speak directly with a licensed InsurixPro specialist for COI and FMCSA filing support.